Three companies sit at the centre of the AI investment thesis, and all three report earnings this week.
Meta Platforms (META), Tesla (TSLA) and SpaceX (SPCX) are each at a different stage of converting AI spending into revenue, and Dan Ives at Yorkville Ives argues that what they say over the next 72 hours will determine whether the AI trade gets its validation moment or faces another round of uncomfortable questions about returns on capital.
Meta (META): the Muse question
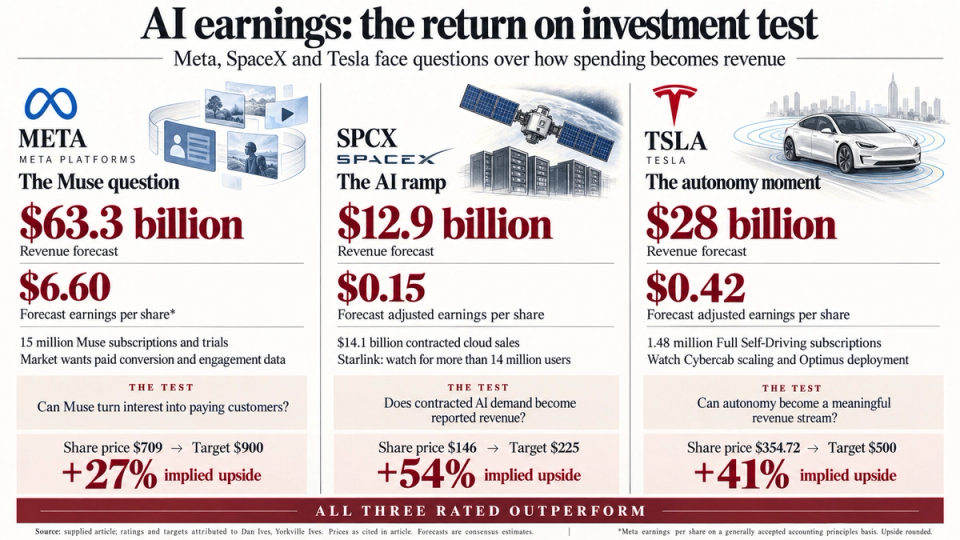
Meta reports after the close on Tuesday with consensus sitting at $63.3 billion in revenue and GAAP earnings per share of $6.60, against guidance of $61 billion to $64 billion.
The number that moves the stock will not be the headline revenue figure.
Muse, Meta's AI content and subscription platform, passed 15 million subscriptions and trials before the quarter closed, making this the first print in which it is a product in market rather than a promise.
What the market wants is a paid conversion number, an engagement data point, or any metric that shows Muse is a business rather than a feature.
Ives also flags 2027 spending guidance as a key moment, with Meta's capex expected near $41 billion for the full year and pressure building on management to demonstrate that the investment has a return.
His price target is $900 against a current price of $709, implying 27% upside.
SpaceX (SPCX): the AI ramp
SpaceX reports tomorrow with consensus at $12.9 billion in revenue and adjusted EPS of $0.15, which would be the company's first profitable quarter on an adjusted basis.
Starlink subscriber growth is one watch item, with the target being whether the network pushes past 14 million users from 12 million in June while average revenue per user holds near $66.
The bigger story is the AI segment, where the Anthropic compute agreement contributes a full quarter for the first time, and $14.1 billion of contracted cloud sales should begin showing in reported numbers.
Read more
- 27/04/26Big Tech earnings arrive this week with AI spending and monetisation under the microscope
- 21/04/26Tesla's Wednesday earnings call is really about two things: robotaxis and the AI bet
- 30/01/26The Magnificent: As Apple, Microsoft, Meta and Tesla reported earnings, markets looked for AI's payoff window
SpaceX is targeting roughly 10 gigawatts of compute capacity by the end of 2027 from 1.4 gigawatts in June, supported by a $47.5 billion backlog.
Ives carries a $225 price target against a current price of $146, implying 54% upside.
Tesla (TSLA): the autonomy moment
Tesla reports Tuesday after the close, with consensus at $28 billion in revenue, adjusted EPS of $0.42 and an automotive gross margin of 17.65%.
The quarterly numbers are secondary to the roadmap update.
Full Self-Driving (FSD) had 1.48 million active subscriptions when Tesla exited June, with an attach rate above 55% on new North American deliveries and paid robotaxi miles approaching 2.5 million across six cities.
The market wants evidence that Cybercab is scaling, that Optimus is moving toward commercial deployment, and that autonomy is converting from a story into a revenue line.
Ives has a $500 target against a current price of $354.72, implying 41% upside.
All three carry Outperform ratings.