Netflix shares are down 6% after hours, and Yorkville analyst and Wall Street's tech bull Dan Ives captured the mood: the subscriptions moved forward, the advertising story moved back.
He kept its In Line rating and $75 price target, but the framing tells you everything about why investors sold. Netflix needs all three of its growth engines, subscription, advertising and engagement, firing together.
This quarter delivered one and a half.
The numbers themselves were fine. Revenue of $12.87 billion and earnings of $0.87 per share both beat forecasts.
Operating margins came in ahead of guidance, helped by the timing of expenses.
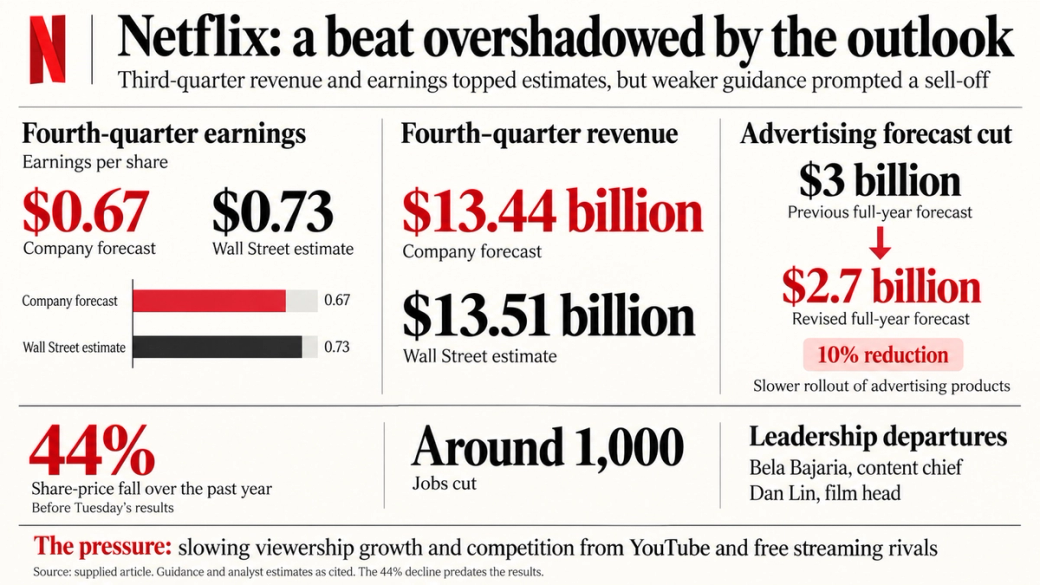
But the fourth-quarter outlook disappointed. Netflix guided for earnings of $0.67 per share against Wall Street's $0.73, and revenue of $13.44 billion against expectations of $13.51 billion.
The bigger blow was advertising. Netflix cut its full-year ad revenue forecast from $3 billion to $2.7 billion, blaming a slower-than-expected rollout of ad products. At a premium multiple, a 10% miss against the full-year target is not a footnote.
There are genuine positives. UCAN revenue accelerated, retention improved across every region and India delivered its biggest quarter of paid net additions. Free cash flow was solid and the buyback is running hard, with $4.8 billion repurchased in the quarter.
The stock was already down 44% over the past year before Tuesday's print. Yorkville will be listening closely to the management call.
Read more about Streaming